Goldendoodle Insurance Premiums by Adult Weight
Bringing a Goldendoodle into your life is pure joy, but let's be real – the financial side can be a maze, especially when it comes to something as crucial as pet insurance. Many new owners get a shock when they start looking at policies, realizing that the size their adorable puppy will grow into plays a surprisingly large role in how much they'll pay each month. This guide will walk you through exactly how your Goldendoodle's adult weight impacts those insurance premiums and what you can expect.
Why Your Goldendoodle's Adult Weight Dictates Insurance Premiums
It might seem unfair that a twenty-pound Goldendoodle and an eighty-pound Goldendoodle could have vastly different insurance costs, but there's a very logical, if sometimes frustrating, reason behind it. Insurers look at risk, and for dogs, weight is a significant indicator of potential veterinary expenses. Larger dogs often cost more to treat, from medication dosages to surgery complications.
The Basic Math of Larger Dogs and Higher Costs
Think about it this way: a tiny Toy Goldendoodle that needs antibiotics for an ear infection will require a much smaller dose than a massive Standard Goldendoodle facing the same issue. This principle extends to almost every aspect of veterinary care. Anesthesia, pain medication, surgical sutures, even the amount of IV fluids needed – everything scales up with body weight.
Consider a worst-case scenario like a broken leg. The surgical plates and screws required to fix a tibia in a 70-pound Standard Goldendoodle are considerably larger and more expensive than those for a 20-pound Mini Goldendoodle. Diagnostic imaging, such as X-rays or MRI scans, might also be more complex or require more images for a larger dog to get a full picture, though this difference is less pronounced than medication or hardware. So, while your big, cuddly Goldendoodle brings immense love, it also brings a higher potential bill for the insurance company, which naturally translates to higher premiums for you. It's a tough pill to swallow when you're just looking at your sweet pup, but it's the reality of veterinary economics.
The Link Between Size and Common Goldendoodle Ailments
Beyond just the basic scaling of treatment costs, many health issues common to Goldendoodles and their parent breeds (Golden Retrievers and Poodles) have a stronger association with larger body sizes. For instance, joint problems like hip and elbow dysplasia, which can plague Goldendoodles, are often more severe and require more extensive (and expensive) interventions in bigger dogs due to the increased stress on their joints. You can learn more about specific risks in our article on Goldendoodle Hip Dysplasia at 15 to 20 Percent.
Even issues like bloat (gastric dilatation-volvulus), a life-threatening condition where the stomach twists, are overwhelmingly seen in large, deep-chested breeds, which includes many Standard Goldendoodles. While a Mini Goldendoodle can certainly get bloat, the risk is significantly higher for their larger counterparts. When insurers calculate risk, they factor in these breed-specific and size-specific predispositions. This is also why factors like a dog's age and even whether a Neuter Timing That Depends on Goldendoodle Size is done later in life can influence long-term health and thus insurance costs.
Estimating Goldendoodle Insurance Premiums by Size Category
So, what can you actually expect to pay? It's not a one-size-fits-all answer, because there's a wide range of Goldendoodle sizes, and each comes with its own general premium bracket. It's important to remember these are estimates; your exact quote will depend on many other factors, which we'll dive into shortly.
Toy and Mini Goldendoodle Premiums
For Toy Goldendoodles, typically weighing under 25 pounds, and Mini Goldendoodles, usually in the 25-45 pound range, you're generally looking at the lower end of the premium spectrum. Because their overall treatment costs are typically less, insurers can offer more competitive rates.
You might find premiums for these smaller Goldendoodles ranging from $30 to $60 per month for accident and illness plans. Of course, this can fluctuate based on your location and the specific plan you choose (deductible, reimbursement percentage), but it serves as a good starting point. These smaller dogs are still prone to some issues, like patellar luxation, so getting good coverage is still vital. However, the sheer volume of medication or surgical supplies needed will usually be less than for their larger relatives.
Medium and Standard Goldendoodle Premiums
Stepping up in size to Medium Goldendoodles (45-60 pounds) and Standard Goldendoodles (60+ pounds, often reaching 80-90 pounds or more), you'll see a noticeable jump in premiums. These are the dogs where the increased cost of medication, anesthesia, and potential surgeries really starts to factor in heavily.
Expect monthly premiums for Medium Goldendoodles to be in the $50 to $80 range, and for Standard Goldendoodles, it could be anywhere from $70 to $120+ per month. This is where the higher incidence of conditions like hip and elbow dysplasia really gets accounted for. Companies like Healthy Paws, for example, will use an algorithm that considers these factors very carefully. When you're budgeting for a What a Goldendoodle Costs a Year With Grooming In, don't forget this significant recurring expense. It's not uncommon for an owner of a large Goldendoodle to face annual premiums exceeding $1000, which can feel like a lot but is a fraction of what a major surgery could cost.
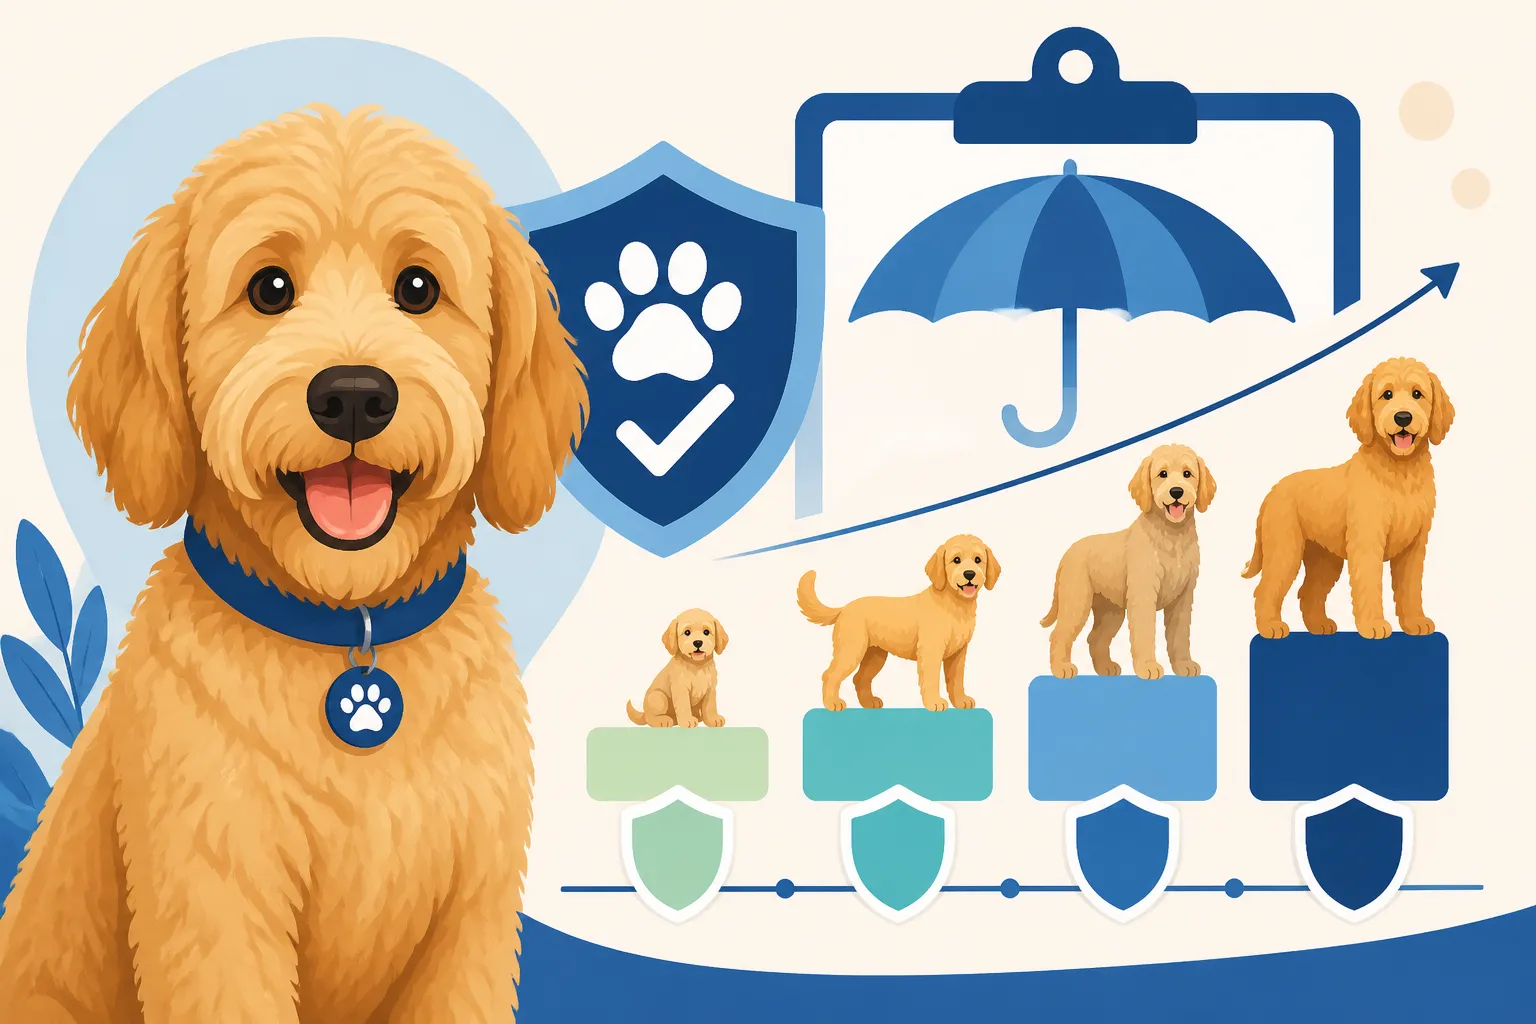
Here's a general idea of how adult weight categories might influence monthly premiums:
| Goldendoodle Size Category | Typical Adult Weight Range | Estimated Monthly Premium Range | Common Health Concerns Amplified by Size |
|---|---|---|---|
| Toy Goldendoodle | Under 25 lbs | $30 – $60 | Dental crowding, Patellar Luxation |
| Mini Goldendoodle | 25 – 45 lbs | $40 – $75 | Patellar Luxation, Allergies |
| Medium Goldendoodle | 45 – 60 lbs | $50 – $80 | Hip/Elbow Dysplasia, Hypothyroidism |
| Standard Goldendoodle | 60+ lbs | $70 – $120+ | Hip/Elbow Dysplasia, Bloat, Cancer |
Remember, these are ballpark figures. Always get a personalized quote for your specific dog.
Other Factors Influencing Your Goldendoodle's Insurance Premiums
While adult weight is a big piece of the puzzle, it's not the only factor insurance companies consider. Several other variables can significantly impact the final price you'll pay for your Goldendoodle's policy. Understanding these can help you better manage costs and choose the right plan.
Age and Location Play a Huge Role
Your Goldendoodle's age is one of the most critical factors. Just like with human health insurance, the older your pet gets, the higher the risk of developing age-related illnesses, and therefore, the higher the premiums. Enrolling a Goldendoodle puppy as early as possible, ideally around 8 weeks old, will secure you lower rates that often carry over for years. Waiting until your Goldendoodle is 5 or 6 years old, or even a Senior Goldendoodle Care After the Age of Nine, will mean substantially higher premiums and potentially more exclusions for pre-existing conditions. Many policies have an "enrollment age limit," so don't wait too long.
Where you live also makes a difference. Veterinary costs vary dramatically by region. A procedure in a major metropolitan area like New York City or Los Angeles will almost certainly cost more than the same procedure in a rural area in the Midwest. Insurance premiums reflect these regional vet cost averages. If you move, your premiums may be adjusted to match the new area's rates. It's a common frustration that can feel like an arbitrary charge, but it reflects real-world differences in operational costs for vet clinics.
Goldendoodle Breed Classification and "Designer Dog" Status
One unique challenge for Goldendoodle owners is their status as a "designer crossbreed." Since the Goldendoodle is not recognized by major kennel clubs like the AKC, insurers don't have a single, standardized "breed" to classify them under. This can sometimes lead to them being categorized as "mixed breed" or "Goldendoodle" specifically, but the underlying risk assessment still draws heavily from the parent breeds.
This lack of formal recognition means that insurers often look closely at the health predispositions of Golden Retrievers and Standard Poodles. For instance, the Golden Retriever side brings a higher risk of certain cancers, while the Poodle side can contribute to conditions like Addison's disease or certain eye problems. These inherited risks, regardless of "hybrid vigor" claims, are part of the actuarial calculation. It's why many owners specifically seek out a policy that covers Insuring a Goldendoodle That No Registry Recognizes without issue. When looking at providers like Chewy's pet insurance offerings or policies from Healthy Paws, they are well-versed in covering popular crossbreeds like Goldendoodles.
Deductibles, Reimbursement Rates, and Annual Limits
Beyond the base premium, the structure of your policy itself will heavily influence your out-of-pocket costs and, by extension, your monthly payments.
- Deductible: This is the amount you pay first before your insurance kicks in. A higher deductible means a lower monthly premium, but you'll pay more upfront if your Goldendoodle needs care. Common deductibles range from $100 to $1,000. For example, if you choose a $500 deductible and your Goldendoodle has a $2,000 ear infection treatment, you'll pay the first $500. For recurring issues like Goldendoodle Ear Infections Under a Furnished Ear, this could be a yearly expense.
- Reimbursement Rate: This is the percentage of the eligible vet bill that the insurance company pays after your deductible is met. Common rates are 70%, 80%, or 90%. A 90% reimbursement rate means higher monthly premiums but less out-of-pocket expense when a claim is filed. Using the previous example, if your treatment was $2,000, and you had a $500 deductible with an 80% reimbursement, you'd pay $500, and the insurer would pay 80% of the remaining $1,500 ($1,200), leaving you to pay $300 more. This adds up to $800 out of pocket.
- Annual Limit: Many policies have a maximum amount they will pay out in a given year. This could range from $5,000 to unlimited. Unlimited annual payouts usually come with the highest premiums but offer the most peace of mind for catastrophic events, like if your Goldendoodle needs Goldendoodle Hip Surgery Costs or cancer treatment, which can run into many thousands of dollars.
Carefully consider your budget and risk tolerance when selecting these options. A lower monthly premium with a high deductible and low reimbursement might seem appealing, but it could leave you with a huge bill if your Goldendoodle faces a serious health crisis.
Choosing the Best Goldendoodle Insurance Policy
Navigating the world of pet insurance can feel overwhelming, but with a Goldendoodle, it's truly an essential part of responsible ownership. Their delightful personalities and unique health considerations mean that having a solid plan in place can save you immense financial and emotional stress down the line.
Comparing Providers and Reading the Fine Print
Don't just jump at the first quote you see. Take the time to compare several reputable pet insurance providers. Companies like Healthy Paws, Embrace, Figo, Lemonade, and even options through platforms like Chewy, all offer various plans. Look for companies that clearly define their coverage for crossbreeds and have a good track record for processing claims efficiently.
When comparing, pay close attention to:
- Coverage for hereditary and congenital conditions: These are crucial for Goldendoodles, given the predispositions from both parent breeds. Make sure hip dysplasia, elbow dysplasia, certain cancers, and eye conditions are covered.
- Waiting periods: Most policies have waiting periods before certain conditions are covered (e.g., 14 days for illnesses, 6 months for orthopedic conditions). Ensure these align with your expectations.
- Exclusions: Understand what isn't covered. Pre-existing conditions are almost always excluded. Some policies might have specific exclusions for certain breed-related issues if not properly defined for crossbreeds. It's crucial to understand The Goldendoodle Conditions Insurers Exclude so you're not caught off guard.
- Customer service reputation: Read reviews. You want a company that is responsive and helpful when you're in a stressful situation with your pet.
Don't hesitate to call the insurance companies directly and ask questions specific to Goldendoodles, especially regarding how they classify the breed and what their typical payout experience is for common Goldendoodle issues like allergies or ear infections.
Enrolling Early and Maintaining Continuous Coverage
The golden rule of pet insurance (pun intended!) is to enroll your Goldendoodle when they are a puppy. This helps you lock in lower premiums and avoids pre-existing condition exclusions for future ailments. If your puppy develops a condition before you have insurance, that condition will likely be excluded from coverage for life. Even if it's something as common as Goldendoodle allergies, getting coverage before symptoms arise is key.
For example, if you wait until your Goldendoodle is two years old and then enroll, and they've already had a nasty ear infection, future ear infection treatments might be deemed a pre-existing condition and excluded. However, if you enroll them at 10 weeks old and an ear infection occurs a year later, it would typically be covered (assuming the waiting period has passed). This continuity of coverage is incredibly important, especially as your Goldendoodle ages and is more prone to health issues. Regular vet check-ups, including Goldendoodle Vaccination and Puppy Health Checks, are also important as insurers will want to see that your pet is receiving routine care.
Considering Wellness Plans vs. Accident & Illness
Most pet insurance plans focus on accident and illness coverage, which covers unexpected veterinary emergencies, surgeries, chronic conditions, and diagnostic tests. This is where the real value lies for potentially high-cost events like Goldendoodle Knee Surgery Costs by Size or extensive cancer treatments.
However, some providers, like Ollie, a popular fresh dog food delivery service, often partner with pet insurance companies or offer wellness add-ons to their own plans. Wellness plans are typically separate or optional add-ons that cover routine care like annual exams, vaccinations, heartworm prevention, and dental cleanings. While these costs are predictable and generally lower, a wellness plan can help spread out those expenses.
Deciding between accident & illness alone or adding a wellness plan depends on your budget and how you prefer to manage predictable costs. For many Goldendoodle owners, the priority is covering the unexpected, expensive health crises, making a robust accident & illness plan the primary focus. However, if you want help budgeting for routine care, a wellness add-on can be a good choice, especially considering the ongoing needs for things like preventative ear cleaning or regular parasite control that are part of standard Goldendoodle care.
Ultimately, investing in pet insurance for your Goldendoodle is an investment in their long-term health and your peace of mind. While the premiums vary by size, age, and location, finding a policy that fits your budget and covers the specific needs of your beloved Goldendoodle is absolutely worth the effort.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.